
Games industry reviews release schedule after global rise in cost of vital components

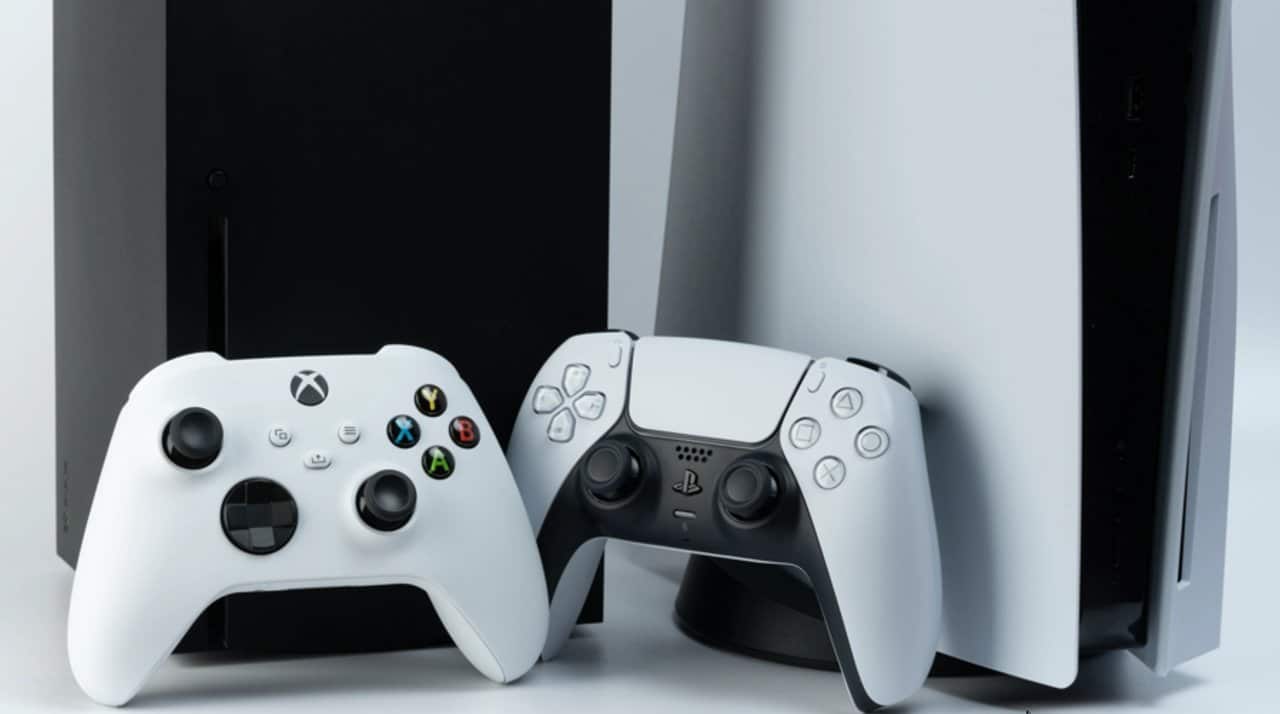
The strategic planning of the largest electronic entertainment companies in the world is undergoing a profound restructuring due to fluctuations in the semiconductor market. Fabricantes of consoles, which historically operate with well-defined hardware renewal cycles, now face a financial obstacle imposed by the excessive valuation of random access memories. Competition for computing resources, intensified by the exponential growth of generative artificial intelligence tools, has created a barrier to entry for the mass production of next-generation home devices.
Executives and engineers at Sony and Microsoft are carefully reviewing development roadmaps for successors to current platforms. The initial forecast, which indicated a generational transition for mid-2027 or 2028, loses strength given the prohibitive costs of essential components. The economic viability of launching a new device directly depends on the ability to offer a significant technological leap at a price accessible to the end consumer, an equation that has become complex in the current inflationary technology scenario.
Scarcity does not just refer to the physical lack of products, but to the priority allocation of existing stocks to corporate sectors willing to pay higher amounts. The server and data center segment, driven by the artificial intelligence race, absorbs a large part of the global production of high-bandwidth memories. Esse diversion of logistical flow forces the gaming industry to reconsider its dates, possibly pushing the arrival of new hardware to the end of the decade, aiming for a time of greater price stability.
Impact of artificial intelligence on the supply chain
The dispute over hardware components has become one of the biggest challenges in maintaining the traditional video game schedule. RAM memories, essential for graphics processing and the execution speed of modern games, have undergone price adjustments that make it impossible to maintain the profit margins expected for home consoles. Diferente than individually sold graphics cards or enterprise servers, video games depend on optimized manufacturing cost to reach the mass market.
Companies focused on developing language models and processing massive data currently dominate orders at major semiconductor factories. The profitability offered by these corporate contracts puts the entertainment sector second in the priority list for silicon foundries. Para compete for the same components, console manufacturers would have to drastically increase the final price of the devices, which could restrict access to a luxury niche and harm the adoption of the platform.
Market analysts point out three direct consequences of this competitive dynamic:
– Increased production costs force companies to subsidize higher amounts per unit sold, increasing financial risk.
– The need to wait for the expansion of global manufacturing capacity so that the supply of components can balance prices again.
– The real possibility that the next generation of consoles will hit the market with suggested prices well above the sector’s historical average.
Strategies to extend the current generation
Faced with the impossibility of launching new hardware in the short term without exorbitant losses, the industry turns its attention to extending the life cycle of the PlayStation 5 and the Xbox Series. The strategy involves maximizing the potential of the current installed base, encouraging the development of software that uses advanced optimization techniques. Software engineering gains prominence over the brute force of hardware, with studios seeking to extract performance through creative solutions and code refinement.
This paradigm shift benefits the consumer by ensuring their current devices remain relevant for longer. Desenvolvedores have invested in scalable graphics engines and image upscaling technologies to deliver high-fidelity visual experiences without the immediate need for a new console. The longevity of current platforms allows the gaming ecosystem to mature, with more robust title libraries and consolidated subscription services.
The maintenance of current console prices also reflects pressure on manufacturing costs. Historicamente, video games undergo price reductions halfway through their life cycle, but volatility in the value of memories and other components has prevented aggressive cuts in this generation. Suggested price stability has become the norm, with one-off promotions replacing the permanent value reductions that were common in past decades.
Perspectives for infrastructure and future launches
The solution to the memory production bottleneck depends on long-term investments in global semiconductor infrastructure. Diversos projects for the construction of new factories are underway on different continents, aiming to decentralize production and increase the total supply of chips. However, the complexity of these facilities requires years to reach full operational capacity, aligning with new launch estimates for 2029 or beyond.
While the industry awaits the normalization of the supply chain, the strategic focus remains on the profitability of services and software sales. The transition to the next generation will only occur when it is possible to guarantee a stable supply of components that allows large-scale production without compromising the financial health of companies. Corporate patience has become essential to avoid troubled launches, marked by a lack of products on the shelves or prices that alienate the consumer public.
The scenario requires adaptation from both manufacturers and development studios, who need to plan their major launches considering a hardware base that will remain on the market for longer than initially anticipated. Innovation continues, but the pace of physical hardware evolution has been forced to slow down to adapt to the new global economic reality dictated by the high demand for artificial intelligence.



