
Semiconductor crisis increases the cost of memory expansion and harms the global gaming market

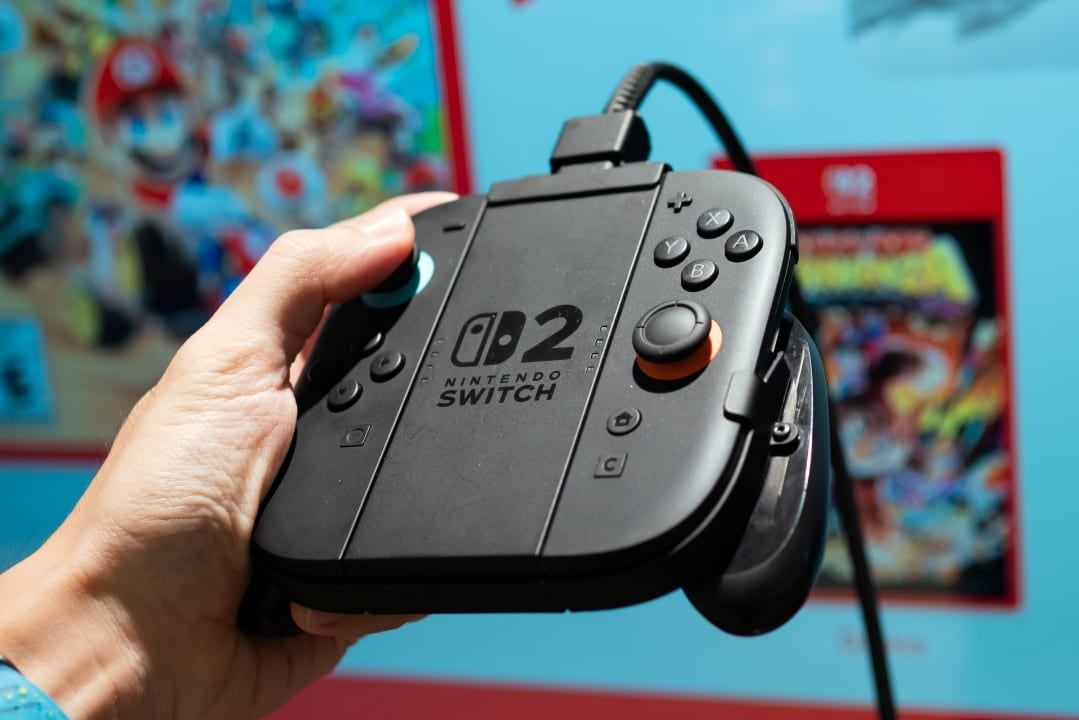
The global electronics and digital entertainment industry faces a severe logistical and manufacturing hurdle due to the continued escalation in NAND memory component costs. The massive demand generated by data centers focused on artificial intelligence has absorbed a large part of the production capacity of the main semiconductor factories around the world. Esse diversion of focus on the supply chain resulted in a significant increase in storage chip manufacturing prices, directly affecting the planning of large technology companies. The video game industry, which relies heavily on fast, affordable storage solutions to keep up with growing software file sizes, finds itself at the center of this financial and structural shift.
The increase in the price of essential parts creates an immediate bottleneck for consumers looking to expand the internal space of their electronic devices. Factory limitations on new devices require the acquisition of expansion cards with prices well above the historical average recorded in international retail.
The current scenario presents specific developments that change the dynamics of consumption in several regions:
– Redução in the acquisition rate of physical games due to the direct transfer of production costs.
– Adiamento of releases by independent studios that depend on accessible media.
– Migração forced into strictly digital formats in emerging markets and secondary retail slices.
Direct effects on software development and distribution
The limitation of internal storage, often set at restricted capacities such as 256 gigabytes in base models of new hardware, becomes a critical problem given the size of recent releases. Desenvolvedores of high-budget software produce files that easily take up a large portion of this quota, requiring immediate external solutions from the user.
Expansion technology via very high-speed cards, necessary to maintain graphics performance and loading times, has undergone severe adjustments on assembly lines. The scarcity of basic components for the manufacture of these peripherals increased the final value on the shelves, deterring the average consumer from purchasing extra space.
Large game publishers evaluate the feasibility of maintaining distribution on physical media in traditional ways. The cost of producing high-capacity cartridges and discs has risen substantially, forcing companies to rethink their market strategies to avoid operational losses in global distribution.
Cost pass-through and the reaction of the consumer market
Some of the largest distributors in the sector have already signaled the need to apply an additional tax on physical products sent to stores. Estima-se que o valor final dos jogos no varejo físico possa sofrer um acréscimo de até vinte dólares para compensar os gastos extras com a fabricação das mídias de armazenamento proprietárias.
This change in the price list directly affects users’ purchasing decisions, who begin to prioritize digital titles during promotional periods or monthly subscription services. The sale of traditional software records a notable slowdown in the main commercial hubs of América, Norte, Europa and Ásia.
Commercial performance and the drop in the annexation rate
Recent retail data indicates a clear shift in behavior among owners of new entertainment hardware. Embora Although the initial pace of handset sales reached significant levels, quickly surpassing the mark of one million and seven hundred thousand units, software consumption did not follow the same upward curve.
The average rate of games purchased by each user registered a significant contraction in the last commercial analysis period. Anteriormente, the market operated with an average of almost four games per console during the launch window, a number that dropped to just over two titles in the current scenario of rising prices.
The high cost of memory accessories is pointed out by retailers as the main factor for this decline in software sales. Sem enough space to install multiple titles simultaneously, consumers are hesitant to purchase new products, preferring to exhaust the content of a single game before investing capital in another launch.
Independent retailers and large department chains report a backlog of generic brand accessories that do not offer the speed required by the new systems. Official and licensed products, on the other hand, remain on the shelves with low turnover exclusively due to the price barrier imposed on customers.
Pressure from artificial intelligence on the supply chain
The prioritization of manufacturing chips aimed at artificial intelligence servers has drastically altered the distribution of resources in Asian and American semiconductor foundries. Contratos memory supply for the corporate sector saw a capacity increase of around ninety percent, absorbing raw material that would be destined for consumer electronics in general. Empresas specialized in assembling memory cards foresee continuous adjustments in their price lists to compensate for the difficulty in acquiring basic inputs on the international wholesale market.
Inflation in the hardware sector affects not only mass storage, but also the random access memory used on the motherboard of devices. Specific Componentes, such as twelve gigabyte RAM modules, showed a forty-one percent increase in their production costs in a short period of months. Essa inflationary pressure squeezes the profit margins of electronics manufacturers, who struggle to maintain the suggested price of their devices without compromising the quality of final assembly or passing on the full value to the public.
Reflections on the financial market and investors’ views
Instability in the supply chain and the consequent change in consumption patterns generate visible apprehension in global financial markets. Analistas of investment banks closely monitor the performance of technology companies, issuing warnings about the risk of a vicious cycle of declining sales. The logic presented by experts in the financial sector suggests that, if the high cost of memory expansion inhibits the purchase of new software, development companies lose the financial incentive to invest in large exclusive productions. Esse cautious scenario is already reflected in the market value of corporations in the interactive entertainment sector, with some recording drops of almost thirty percent in their shares since the beginning of the turmoil in the production chain. The dependence on imported components and the lack of local manufacturing alternatives in the short term keep the level of uncertainty high among shareholders, who demand contingency plans from executive boards to overcome the hardware shortage.
Industry mitigation and adaptation strategies
To overcome the supply crisis and high costs, manufacturers are studying the introduction of cartridges with smaller capacities, specifically aimed at games with less graphic complexity. Essa technical measure aims to serve independent developers who do not need high-cost media to distribute their physical projects.
Another tactic adopted by studios involves extreme optimization of the games’ source code, reducing the final size of the files so that they fit into the devices’ standard internal storage. Equipes entire software engineering suites are dedicated exclusively to advanced compression of high-resolution textures and uncompressed audio files.
The logistics scenario for the coming quarters
The normalization of inventories and the stabilization of component prices depend on the opening of new semiconductor factories, an industrial process that requires time and massive structural investments. Até As global chip supply balances with continued demand from the artificial intelligence sector, the consumer electronics segment will continue to operate under tight profit margins and strict supply control policies.



