Global crude oil prices experienced a notable decline on Friday, January 26, 2025, as the market adjusted following a period of recent gains and contended with reduced trading activity in the aftermath of the New Year’s holiday. This downward trend occurred despite the persistent backdrop of various geopolitical tensions across key producing regions, which traditionally exert upward pressure on prices. Investors largely focused on rebalancing portfolios and navigating a session characterized by thin liquidity, allowing for magnified price movements.
The West Texas Intermediate (WTI) crude for February delivery, traded on the New York Mercantile Exchange (Nymex), concluded the session with a significant drop of 2.76%, or US$1.61, settling at US$56.74 per barrel. This reflected a strong unwinding of earlier positions.
Similarly, Brent crude, the international benchmark, saw its March contract on the Intercontinental Exchange (ICE) in London fall by 2.52%, a decrease of US$1.56, closing at US$60.24 per barrel. While Friday marked a sharp decline, the weekly performance presented a mixed picture, with WTI advancing 0.38% over the five days, contrasting with Brent’s 0.38% weekly retreat, underscoring short-term volatility.
Geopolitical Dynamics Shaping Crude Futures
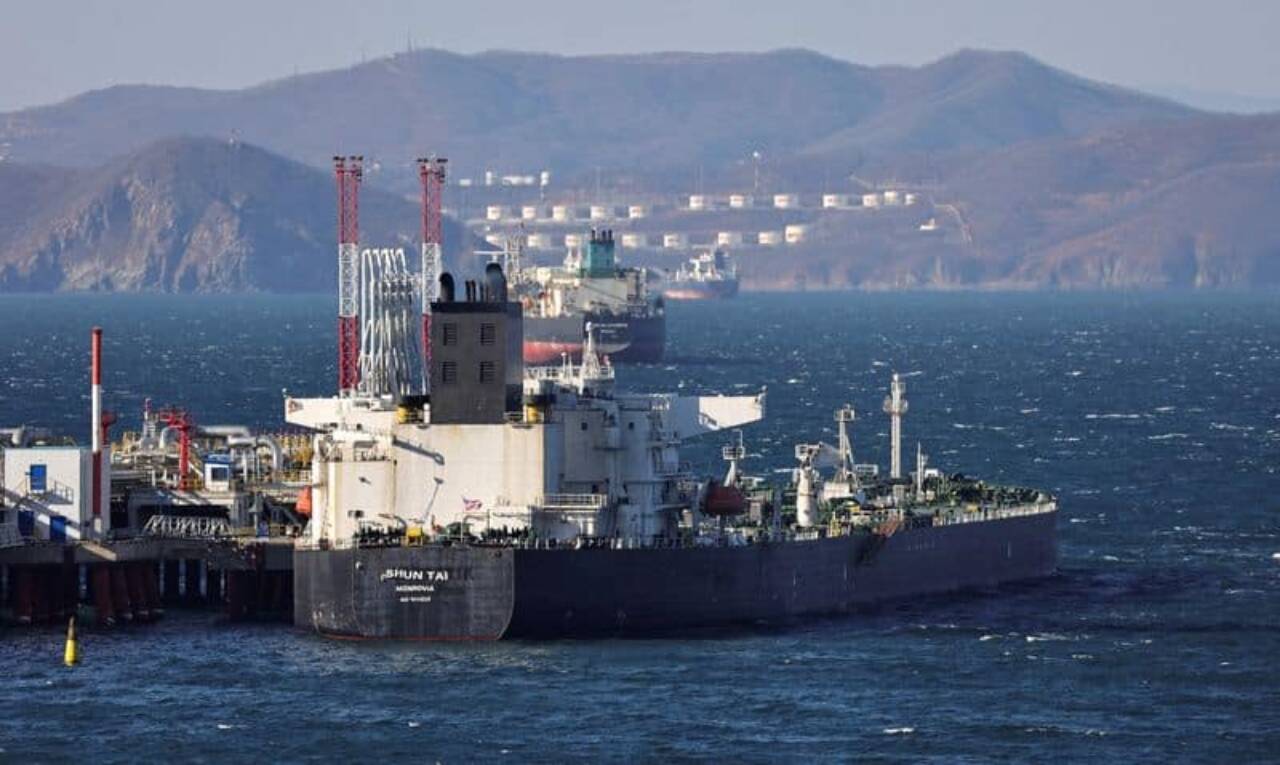
The broader energy market continued to monitor several geopolitical flashpoints, particularly the ongoing apprehension of Venezuelan oil tankers by the United States, which has consistently kept supplies from the Caribbean region under pressure. This maritime enforcement action remains a significant, though localized, factor influencing sentiment. Simultaneously, market participants closely followed developments regarding potential peace agreements between Russia and Ukraine, exercising caution as any progress could shift global supply dynamics.
In Eastern Europe, discussions surrounding a potential peace accord between Russia and Ukraine gained renewed attention as Ukrainian President Volodymyr Zelensky is reportedly scheduled to meet with former President Donald Trump on Sunday, January 28, 2025, to advance negotiations for a ceasefire. According to reports, President Zelensky might even put a peace plan to a national referendum if Russia agrees to a ceasefire lasting at least 60 days, signaling a potentially pivotal moment for regional stability.
Diplomatic Efforts and Regional Standoffs
In parallel to these discussions, statements from Moscow indicated that Russia and Washington were nearing a resolution to the ongoing conflict in Eastern Europe, as affirmed by Russian Deputy Minister of Foreign Affairs, Sergei Ryabkov. Such diplomatic progress, if materialized, could significantly ease geopolitical risk premiums built into oil prices. Conversely, the Kremlin sharply criticized recent US military actions in the Caribbean targeting Venezuela, labeling them as acts of “piracy” and “banditry,” further highlighting the strained relations between the major powers.
These contrasting narratives — potential de-escalation in one region versus heightened rhetoric in another — created a complex environment for crude oil trading. The market weighs the implications of each development on future supply security and global economic stability.
Contrasting Market Forces and Price Influences
The oil market currently faces a delicate balance of bullish and bearish forces, as highlighted by financial analysts. On the positive side for commodity prices, the continued blockade impacting Venezuelan oil exports and the anticipated high demand for travel during the early 2025 holiday period provide some underlying support. However, these are tempered by significant negative factors.
Key negative influences on crude prices include:
* High global oil storage levels, indicating ample supply.
* Progress in Russia-Ukraine negotiations, which could unlock more crude supply.
While the US actions against Venezuela continue to exert pressure on its oil industry, the broader global impact on crude prices appears to be minimal at this juncture, with market fundamentals often overshadowing immediate geopolitical events unless they directly disrupt major supply lines.
Middle East Tensions Persist Amid Broader Concerns
In the Middle East, geopolitical perturbations remained a factor in Friday’s trading session, adding another layer of complexity to the global oil landscape. Israel announced a series of targeted attacks against Hezbollah militant positions in Lebanon, escalating regional tensions. This continued friction in the Levant region underscores the inherent instability that can, at any moment, impact vital oil shipping routes and production facilities.
Concurrently, Iran reported the apprehension of a vessel in the Persian Gulf carrying approximately 4 million liters of smuggled fuel. These interdictions by Iranian authorities are a frequent occurrence in the strategic waterway and serve as a reminder of the constant vigilance and potential for disruption in a region critical to global energy supplies. The ongoing skirmishes and enforcement actions ensure that the Middle East remains a focal point for geopolitical risk analysis within the oil market.
Market Adjustment Drives Price Volatility
The significant drop on Friday for both WTI and Brent underscores how quickly the market can react to shifts in investor sentiment, particularly after a period of strong gains. Profit-taking and adjustments after recent upward momentum played a crucial role, amplified by the reduced trading volume typical of the post-holiday period. This thin liquidity environment often means that even moderate buying or selling pressure can lead to outsized price movements, contributing to overall market volatility.
Early Year Economic Outlook and Oil Prospects
Looking ahead into 2025, the global oil market will continue to navigate a confluence of economic forecasts, supply-demand dynamics, and geopolitical developments. The early January trading patterns, including the observed price adjustments and reduced liquidity, offer insights into the cautious stance adopted by many investors as they recalibrate expectations for the new year. Sustained economic growth in major consumption centers would underpin demand, while any resolution or escalation of current conflicts could dramatically alter the supply outlook, keeping crude prices on a sensitive trajectory.